Profit and Loss: Concepts, Formulas, and Clear Examples
Profit and Loss is the study of how the price paid for an item compares with the price received when that item is sold. The amount paid is called the cost price, or CP. The amount received is called the selling price, or SP. If the selling price is higher than the cost price, there is a profit. If it is lower, there is a loss.
For example, suppose a shopkeeper buys an item for ₹650 and sells it for ₹725. The selling price is ₹75 more than the cost price, so the shopkeeper earns a profit of ₹75.
That basic comparison remains at the centre of the topic. The same idea can include percentages, a marked price, two discounts, free items, damaged goods, false weights or several transactions. We will build these ideas in order so that every price change has a clear meaning.
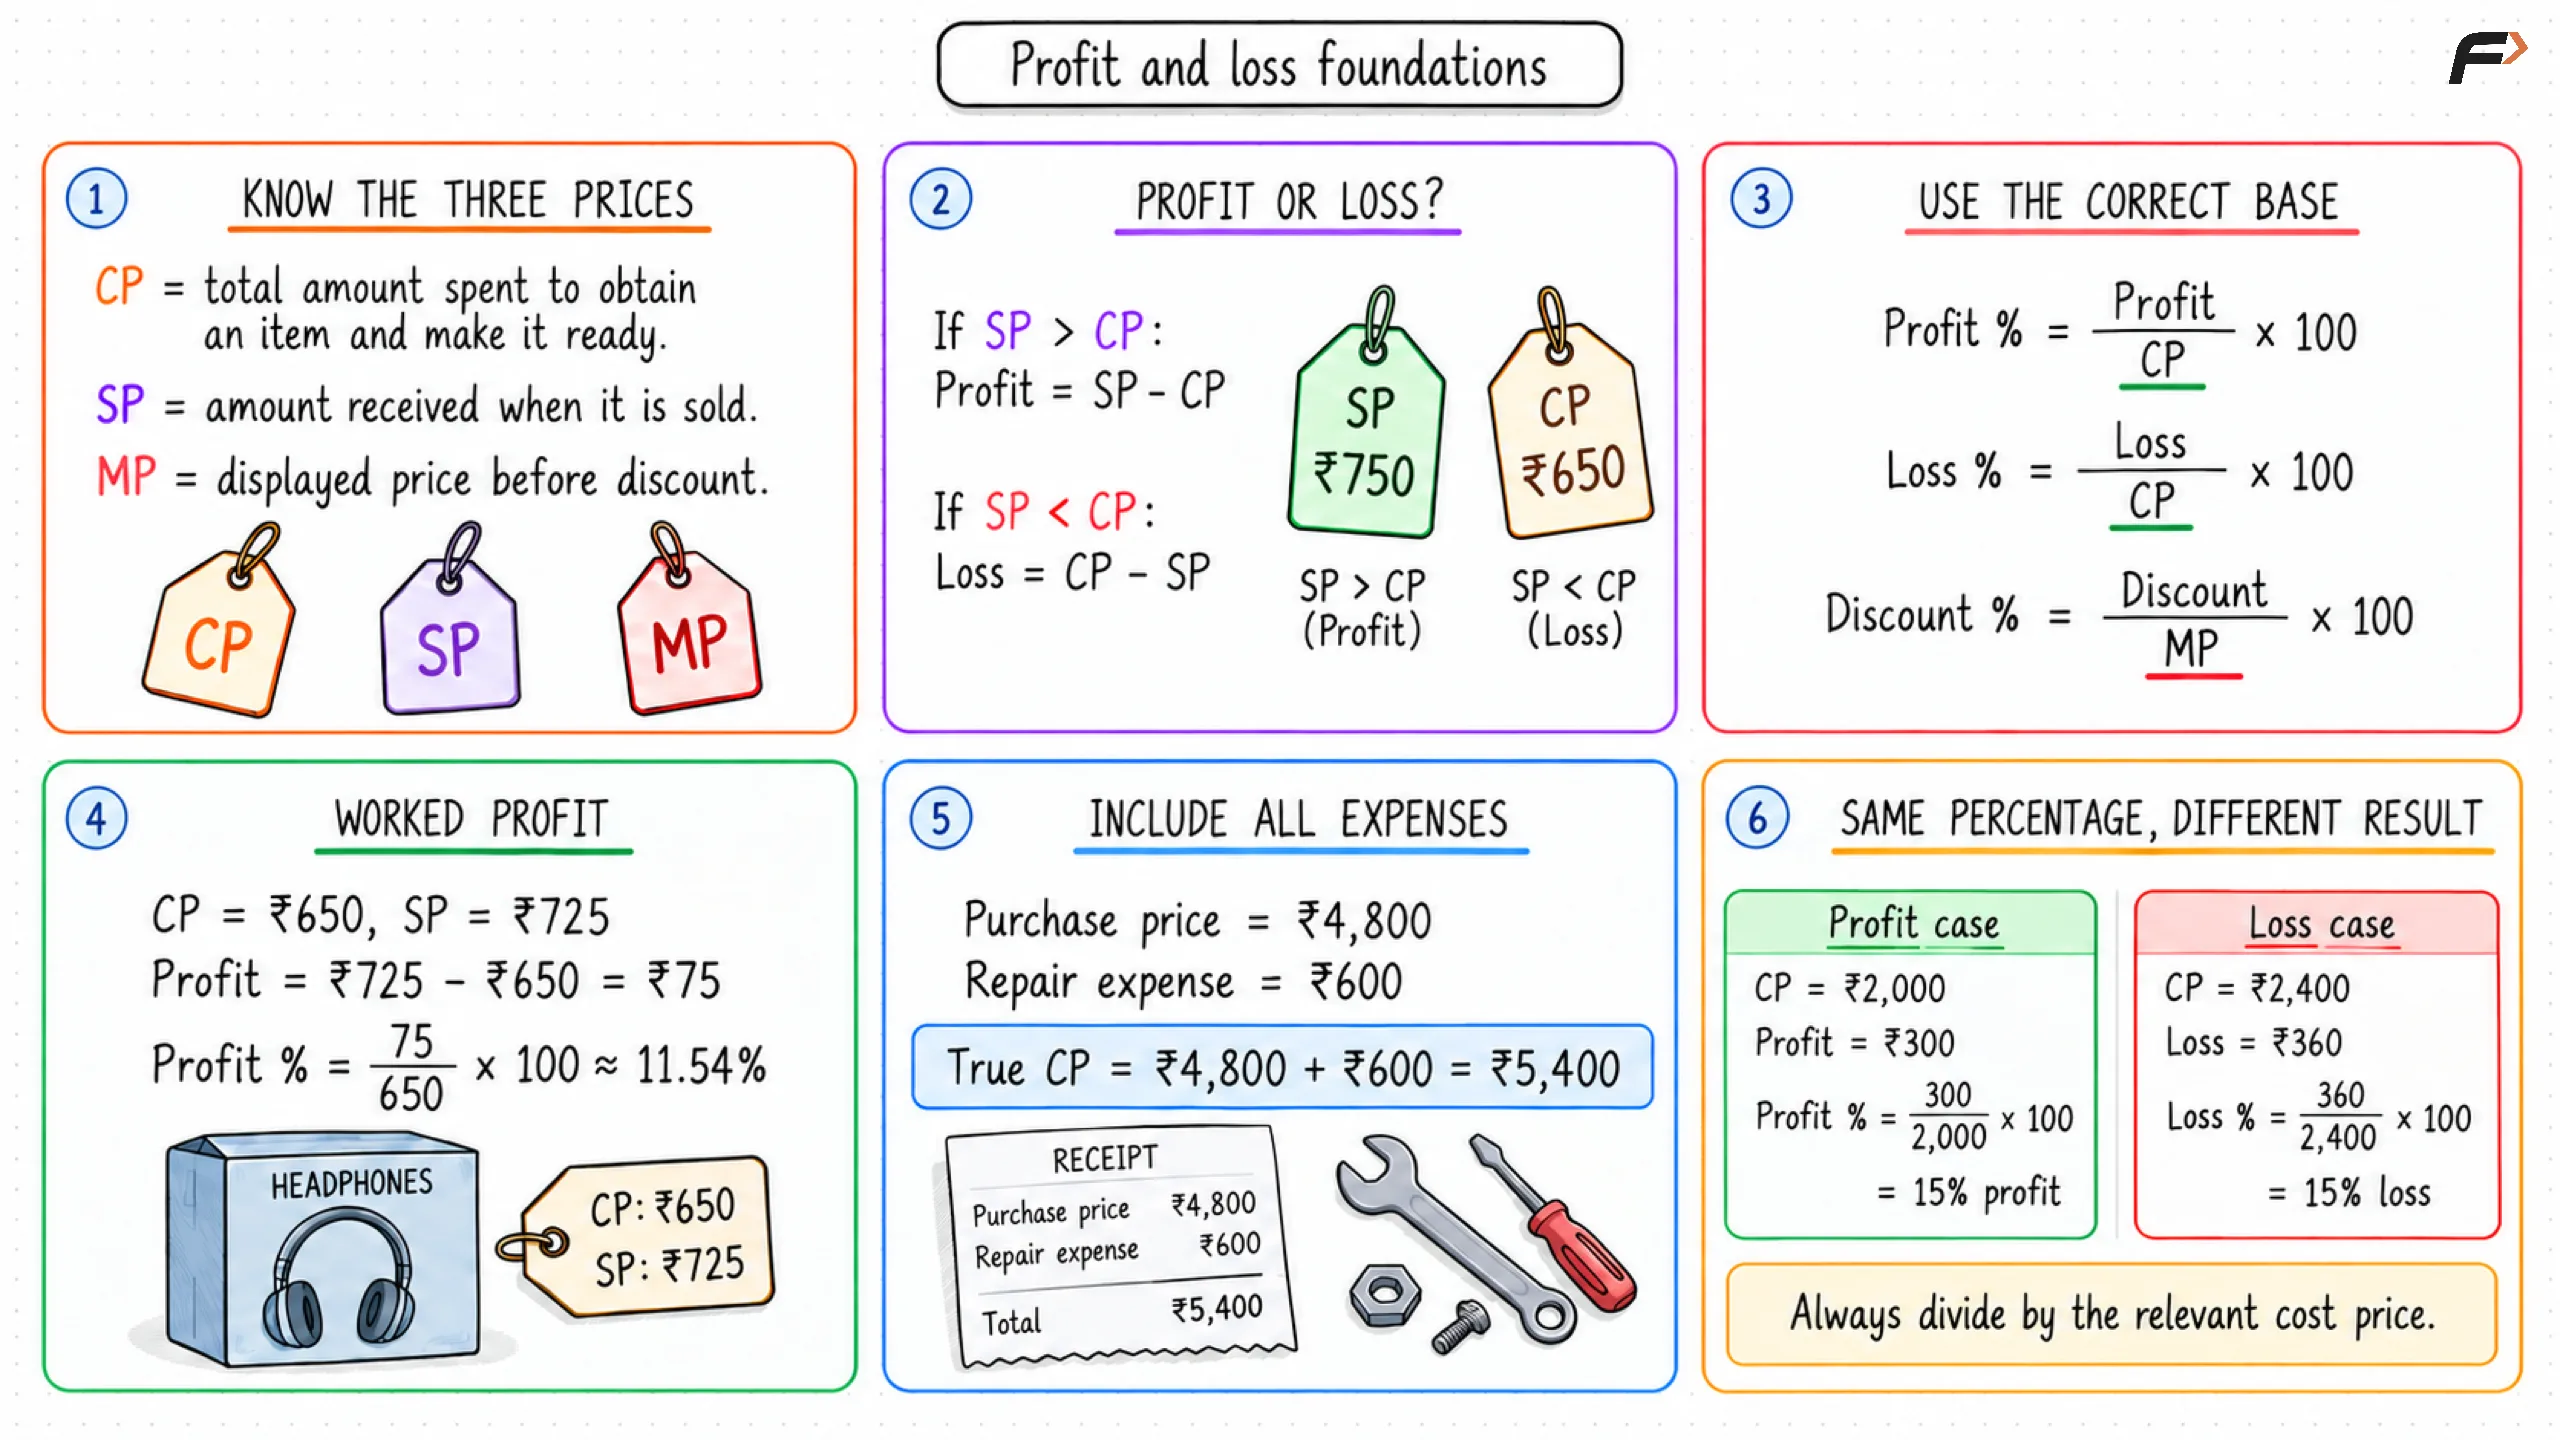
Profit and loss foundations: cost price, selling price, marked price and percentage bases
Cost Price, Selling Price, Marked Price, Profit, Loss, and Discount
Before using formulas, it helps to be clear about the terms.
| Term | Meaning |
|---|---|
| Cost Price (CP) | The total amount spent to obtain an item and make it ready for sale |
| Selling Price (SP) | The amount received when the item is sold |
| Marked Price (MP) | The price written or advertised before a discount |
| Profit | The amount by which SP is greater than CP |
| Loss | The amount by which CP is greater than SP |
| Discount | The amount by which MP is reduced to obtain SP |
The word total matters in the definition of cost price. If a trader buys a machine for ₹4,800 and spends ₹600 on repair and transport, the effective cost price is not ₹4,800. It is:
Any necessary expense made before the sale normally becomes part of the cost price.
The Basic Profit and Loss Formulas
When the selling price is greater than the cost price:
When the selling price is less than the cost price:
Suppose an article costs ₹2,400 and is sold for ₹2,040. Since the selling price is lower, there is a loss:
These formulas find the amount of profit or loss. To compare that amount with the investment, we use a percentage.
Why Is Profit or Loss Percentage Calculated on Cost Price?
A trader invests the cost price. Therefore, profit or loss is measured against that investment.
Suppose a trader buys an item for ₹2,000 and makes a profit of ₹300. The profit percentage is:
Now suppose the cost price is ₹2,400 and the loss is ₹360:
The denominator is CP in both cases. Discount is different because it measures a reduction from the marked price:
Remembering the correct base prevents many mistakes:
- profit or loss percentage uses CP;
- discount percentage uses MP.
Finding Selling Price from Cost Price
If an item is sold at a profit of , its selling price is the cost price plus of the cost price:
Case 1: Selling at a profit
Example: An article costs ₹1,800 and is sold at a profit of . Find the selling price.
The profit is:
So:
The same result comes directly from the multiplier :
If an item is sold at a loss of , the selling price is:
Case 2: Selling at a loss
Example: An article costs ₹3,200 and is sold at a loss of .
Since , the loss is:
Therefore:
Finding Cost Price from Selling Price
Sometimes the selling price and profit or loss percentage are given, and the original cost price must be found. In that situation, reverse the percentage multiplier.
At a profit of :
At a loss of :
Case 1: Reverse a profit
Example: An article is sold for ₹2,760 at a profit of . Here, the selling price is of CP:
Case 2: Reverse a loss
Example: An article is sold for ₹3,230 at a loss of . The selling price is now of CP:
The key is to ask what the known selling price represents. It is percent of CP after a profit and percent of CP after a loss.
Finding Cost Price from the Profit or Loss Amount
The profit or loss amount and its percentage may be known even when SP is not given.
If a profit of ₹450 is of CP, then:
Similarly, if a loss of ₹560 is of CP:
This is simply the percentage formula rearranged. First identify what the given amount is a percentage of, and then divide by the corresponding percentage.
Marked Price and a Single Discount
The marked price is the price displayed before a discount. Therefore:
If the discount rate is :
Case 1: Find the discount amount
Example: An item marked at ₹5,000 is sold for ₹4,250.
The discount percentage is:
Case 2: Discount followed by profit
Example: An item has a marked price of ₹7,200. A discount of is given, and its cost price is ₹5,400. Find the profit percentage.
First find the actual selling price:
Then compare SP with CP:
The discount and profit percentages cannot be directly subtracted because they use different bases.
Markup and Discount Together
A trader may first mark an item above cost price and then offer a discount. Treat the two changes one after another.
If the markup is and the discount is :
Suppose an item costs ₹1,000, is marked above CP, and then sold at a discount.
The final profit is ₹170, so the profit percentage is .
This is why markup minus discount, , is not the answer. The discount is applied after the markup, on a different amount.
Successive Discounts
When two discounts are offered one after another, the second discount is applied to the already reduced price.
For discounts of and :
Example: An article marked at ₹12,000 receives discounts of and then .
After the first discount:
After the second discount:
The final selling price is ₹8,640. The two discounts together are equivalent to:
They are not equivalent to , because the second is not taken from the original marked price.
Changes in Selling Price
When the cost price stays the same, the difference between two profit or loss rates can be converted directly into a percentage of CP.
Case 1: Profit percentage increases
Example: An item is sold at a profit of . If the selling price is increased by ₹640, the profit becomes . Find CP.
The increase in profit rate is:
Since CP has not changed, the ₹640 increase equals of CP:
Case 2: One profit and one loss
Example: The same article would give a profit of at one price and a loss of at another. The difference between the selling prices is ₹1,600.
The total gap is:
Therefore:
The rates are added here because one price is above CP and the other is below CP.
Case 3: A small change in profit rate
Example: A selling price gives an profit. Raising the price by ₹1,250 changes the profit to .
Keeping the fractional value until the final step avoids an inaccurate rounded answer.
Overall Profit or Loss on Several Articles
For several items, add all cost prices and all selling prices before calculating the percentage:
Case 1: Equal cost prices, different results
Example: Two articles cost ₹5,000 each. One is sold at an profit and the other at a loss.
For the first item:
For the second:
So:
The overall profit is ₹300:
Even when the individual percentages look easy to combine, totals provide the safest method. If the cost prices are unequal, simply averaging the percentages will usually be wrong.
Successive Sales and Price Chains
In a chain of transactions, the selling price of one person becomes the cost price of the next. Percentage multipliers make the calculation clear.
Case 1: A loss followed by a profit
Example: A buys an article for ₹15,000 and sells it to B at a loss of . B sells it at a profit of . Compare the final price with A's original cost.
After A's sale:
After B's sale:
Compared with the original ₹15,000, the final price is ₹1,500 higher:
The overall price rise is . A loss followed by a profit is not a rise, because the two percentages act on different prices.
The same method works for any number of sales. Multiply the relevant factors in order.
Additional Expenses Included in Cost Price
Repair, transport, packaging, installation, and similar necessary expenses are included in CP before profit or loss is calculated.
Example: A trader buys a machine for ₹4,800, spends ₹600 on repairs and transport, and sells it for ₹6,210.
Using only the purchase price in the denominator would overstate the actual profit.
Bulk Purchases, Mixtures, and Different Quantities
When goods are bought at different rates, find the total cost rather than taking an unweighted average of the rates.
Case 1: Two purchase rates
Example: A trader buys 40 kg of grain at ₹60 per kg and 20 kg at ₹30 per kg. The entire 60 kg is sold at ₹36 per kg.
So the loss is ₹840:
The purchase rates ₹60 and ₹30 should not be simply averaged because the quantities bought at those rates are different.
Damaged or Unsellable Goods
If part of a stock is damaged, the total cost of the original stock remains the cost base. Only the usable quantity produces revenue.
Example: A trader buys 100 kg of goods at ₹40 per kg. Ten percent is damaged, and the remaining goods are sold at ₹50 per kg.
The full cost is:
Only 90 kg can be sold:
Therefore:
Do not reduce the cost price to the cost of 90 kg. The damaged 10 kg was also purchased and is part of the investment.
“Buy Some, Get Some Free” Offers
A free-item offer changes the number of units given to the customer. Compare the revenue received with the cost of all units handed over.
Case 1: Buy 5, get 2 free
Example: A shopkeeper marks each item above its cost price and offers “Buy 5, get 2 free.” Let the cost of one item be ₹100.
Seven items cost the shopkeeper:
The marked selling price of one item is:
The customer pays for only five items:
Thus the shopkeeper loses ₹100:
A markup does not guarantee a profit when enough units are given free.
Case 2: Buy 3, get 1 free
Example: If the markup is , four items cost , while the revenue is:
The loss is on a cost of :
This unit method works for any “buy , get free” offer.
False Weights and Short Weight
With a false weight, the customer is charged for one quantity but receives a smaller quantity. The cost of the quantity actually delivered is the real cost base.
Case 1: Giving 900 g as 1 kg
Example: Suppose the cost of 1 kg is ₹100. A dishonest trader charges ₹100 but gives only 900 g.
The cost of 900 g is ₹90, while the amount received is ₹100.
The profit is not because the actual cost is ₹90, not ₹100.
Case 2: A discount cancels the short weight
Example: Suppose the marked price per kilogram equals the cost price per kilogram. The trader gives a discount but delivers only 900 g for every kilogram.
Let the listed cost of 1 kg be ₹100. After the discount, the customer pays ₹90. The trader delivers goods that cost ₹90. Therefore, SP equals the actual CP, and there is no profit or loss.
When both discount and short weight appear, calculate the money collected and the cost of the delivered quantity separately.
Cost of Some Articles Equals Selling Price of More Articles
The total cost of one number of articles may be equal to the total selling price of another number.
Example: The cost price of 40 articles equals the selling price of 50 articles. Let the cost price of one article be ₹1.
Then the cost of 40 articles is ₹40. Since this is also the selling price of 50 articles:
The loss per article is ₹0.20 on a cost of ₹1:
Choosing a simple assumed unit keeps this calculation short and easy to check.
Ratios of CP, MP, and SP
If the prices are given as a ratio, treat the ratio parts as actual comparable amounts.
Example: Suppose:
The profit is part on a cost of 5 parts:
The discount is parts on a marked price of 8 parts:
The same three numbers produce different percentages because profit and discount use different bases.
When Profit Is Given as a Percentage of Selling Price
The usual profit percentage is based on CP, but profit can also be stated as a percentage of SP. The percentage base must therefore be identified clearly.
Example: An article is sold for ₹6,000, and the profit is of the selling price.
Therefore:
To convert this into the usual profit percentage on CP:
So a profit equal to of SP is the same as a profit on CP in this example.
A Change in Cost Price While Selling Price Stays Fixed
If CP changes but SP remains the same, recalculate the actual profit using the new cost price. Do not simply adjust the old profit percentage.
Example: An item originally costs ₹6,000 and is sold at a profit of .
Now suppose the cost price falls by , while SP remains ₹7,200.
The new profit is:
Therefore:
The percentage rises by more than five points because both the profit amount and the cost base change.
Data Sufficiency in Profit and Loss
Data sufficiency checks whether the information is enough to produce one definite result. It does not always require the final numerical value.
Use this process:
- Write down the value that must be found.
- Identify the minimum values needed.
- Test each statement separately.
- Combine the statements only if neither works alone.
Case 1: Finding profit percentage
Example: To find profit percentage, we need CP and SP:
If Statement I gives both CP and SP, it is sufficient by itself. If Statement II gives only the marked price, it is not sufficient because neither the discount nor the actual selling price is known.
Case 2: Finding selling price after discount
Example: To find SP after a discount, we need MP and the discount rate. A statement giving only MP is insufficient, and a statement giving only the discount rate is also insufficient. Taken together, they are sufficient.
The aim is not to use every statement. It is to determine exactly which information completes the formula.
A Reliable Profit and Loss Method
When several prices or percentage changes are connected, use the following order:
- Identify CP, SP, and MP from the wording.
- Include additional expenses in CP.
- Note the base of every percentage.
- Convert percentage changes into multipliers when they occur successively.
- For several items, calculate total CP and total SP.
- Find the final money difference.
- Divide by the correct base and then multiply by 100.
For example, if a product is marked above CP and receives two discounts, first write:
where the discount rates are written in decimal form. This keeps every step attached to the price on which it acts.
Formulas and Cheat Sheet
| Situation | Formula or method |
|---|---|
| Profit amount | |
| Loss amount | |
| Profit percentage | |
| Loss percentage | |
| SP at profit | |
| SP at loss | |
| CP from SP at profit | |
| CP from SP at loss | |
| Discount | |
| SP after discount | |
| Two successive discounts | Multiply both remaining-price factors |
| Several articles | Compare total SP with total CP |
| False weight | Compare money received with cost of quantity delivered |
| Free-item offer | Compare revenue from paid units with cost of all units given |
Safe Shortcuts
- Use a selling-price multiplier: At profit, . At loss, change the plus sign to a minus sign.
- Reverse a percentage by dividing: If SP and the profit or loss rate are known, divide SP by the correct multiplier to get CP. Do not simply subtract the percentage from SP.
- Combine two discounts safely: Successive discounts of and give an effective discount of percent.
- Multiply markup and discount factors: If an item is marked up and then discounted, multiply the two factors. The two rates use different price bases, so subtracting them is unsafe.
- Use the equal-selling-price result only under its condition: If two articles are sold for the same SP, one at profit and the other at loss, the overall result is a loss of .
- Combine actual totals: For several articles, add all cost prices and all selling prices first. Overall profit or loss comes from those totals, not from an ordinary average of the percentages.
- Use a convenient base: When only percentages or a false weight are given, assume a CP of ₹100 or a standard quantity of 100 units. The final percentage remains the same.
A shortcut is safe only when CP, SP, MP, and the percentage base are clear. It should shorten correct reasoning, not replace it.
Frequently Asked Questions
Are profit and loss percentages always calculated on cost price?
Yes, unless the question explicitly says otherwise. The standard profit or loss percentage uses cost price because CP is the amount invested. A phrase such as “profit is of selling price” changes the base and must be handled exactly as stated.
Can markup and discount percentages be subtracted?
Not directly. Markup is applied to CP, while discount is applied to MP. Use successive multipliers to find the final selling price and then compare it with CP.
Can two successive discounts be added?
No. A discount of followed by is an effective discount of , not . The second discount is applied to the price remaining after the first.
Why do false-weight questions use the cost of the delivered quantity?
That is the quantity the trader actually parts with. If 900 g costs ₹90 and the trader receives ₹100, the ₹10 profit is earned on an actual cost of ₹90.
How should I solve questions involving several products?
Find the combined cost price and combined selling price. Then calculate the overall profit or loss on the total cost. Do not average individual percentages unless their cost bases are equal and the averaging is justified.
Conclusion
Profit and Loss becomes manageable when every percentage is connected to the correct price. Profit and loss use cost price as their base, while discount uses marked price. After that, most advanced-looking questions reduce to one of a few ideas: reverse a percentage, multiply successive factors, combine total costs and sales, or compare the money received with the actual quantity supplied.
Start by labelling CP, SP, and MP. Then work in actual amounts before calculating the final percentage. That approach remains reliable across direct questions, discounts, price changes, free-item offers, damaged stock, false weights, ratios, successive sales, and data-sufficiency problems.